What Is the Fair Debt Collection Practices Act
by Attorney S. Zachary T. Brock
Table of Contents
Unfair Debt Collection and the FDCPA in Indiana
Debt collectors are allowed to contact consumers about legitimate debts, but they do not have unlimited freedom to threaten, mislead, embarrass, or repeatedly pressure someone into paying. The Fair Debt Collection Practices Act, usually called the FDCPA, is a federal law that sets rules for many third party debt collectors and gives consumers protections when collection behavior crosses the line.
For people in Indianapolis and Central Indiana, understanding the FDCPA can make a stressful situation easier to evaluate. A collector’s demand may sound urgent, but urgency does not erase your rights. You can ask questions, document communications, dispute debts when appropriate, and get legal advice before agreeing to a payment you cannot afford.
The Fair Debt Collection Practices Act protects consumers from abusive and deceptive collection tactics; learn more on our unfair debt collection page. Brock Legal, LLC helps Indiana consumers review collection conduct, debt lawsuits, credit reporting problems, and bankruptcy options. The right response depends on who is collecting, what they are saying, whether the debt is accurate, and whether a larger financial problem also needs to be addressed.
Bankruptcy Attorney Guide to Who the FDCPA Covers
The FDCPA generally regulates debt collectors collecting consumer debts, but coverage depends on the identity and role of the company contacting you. A third party collection agency collecting a credit card, medical, personal loan, or other consumer account is a common example. Debt buyers and collection law firms can also be subject to the law in qualifying circumstances.
• Identify the company contacting you and whether it is collecting its own account or collecting for someone else.
• Save the original creditor name, claimed balance, account reference, mailing address, and every written notice.
• Keep court papers separate from ordinary collection letters because a lawsuit creates deadlines that must be answered.
• Review whether the obligation is personal, family, or household debt, because business obligations can be treated differently.
The law is focused on personal, family, or household debts. The rules can differ when the original creditor is collecting its own account rather than using a third party collector. That distinction is one reason it is important to identify the company before deciding that a communication violates the FDCPA.
A bankruptcy attorney can also help determine whether the collection problem is one account or part of a broader debt situation. If several creditors are suing, garnishing wages, or sending accounts to collections, bankruptcy may deserve consideration alongside individual consumer claims.
Debt Relief Rights Against Abusive Collection Conduct
The FDCPA restricts a range of abusive, unfair, and deceptive conduct. The exact facts matter, but consumers should pay attention when a collector’s behavior seems designed to frighten rather than communicate accurate information.
• Repeated calls intended to harass can be a warning sign. Frequency, pattern, timing, and what happens during the calls can all matter.
• Threats or abusive language can raise concerns. A collector should not use profanity, threaten violence, or claim consequences it has no legal right or actual intention to pursue.
• Misrepresentations are another major issue. Collectors should not lie about the amount or legal status of a debt or falsely suggest arrest.
• Improper contact with other people can also be significant. Collection law limits what collectors may communicate to family members, coworkers, neighbors, or employers in many circumstances.
Keep evidence instead of relying on memory. Screenshots, call logs, voicemails, letters, emails, text messages, and envelopes can help establish a timeline. Write down what was said while it is still fresh. If a collector changes its story, the record can help show exactly what information you received and when.
Consumer Finance Assistance When a Collector Has the Wrong Debt
Sometimes the biggest problem is not tone. It is accuracy. You may not recognize the account, the balance may be wrong, the debt may belong to someone with a similar name, or a collector may be pursuing an account affected by identity theft.
• Compare the collection notice with your own records, including the original creditor, dates, balance, and payment history.
• Ask for information needed to identify the debt rather than giving sensitive financial information to an unknown caller.
• Preserve settlement letters, payment records, fraud reports, or earlier disputes that help explain why the balance is wrong.
• If a lawsuit has been filed, respond to the court deadline even while the debt is being disputed.
If a collector has violated your rights, you may have legal options beyond bankruptcy through our consumer finance assistance services. Start by comparing the collection notice with your own records. Do not ignore a debt simply because you dispute it. If a lawsuit has been filed, court deadlines still apply.
Credit reporting can create a separate problem. A collection account may appear on one or more credit reports with an incorrect balance, status, date, or owner. Disputing inaccurate credit information can involve different federal protections than the FDCPA, so it helps to separate collection conduct from reporting accuracy.
Bankruptcy Lawyer Options When Debt Is Still Valid
A collector can behave lawfully while the underlying debt is still unaffordable. In that situation, the question changes from whether the collector violated the law to how you can resolve the financial obligation.
Bankruptcy may be appropriate when collection activity is part of a larger debt problem. Filing a bankruptcy case generally triggers the automatic stay, which stops many covered collection actions. Chapter 7 may discharge many qualifying unsecured debts for eligible filers. Chapter 13 can create a repayment plan and may help people protect important property while addressing arrears and unsecured balances.
Debt settlement or direct negotiation may be another option for some consumers. The best choice depends on income, assets, number of creditors, pending lawsuits, garnishments, tax consequences, and the amount available to resolve accounts.
Do not let the loudest collector determine your entire financial strategy. A demand for immediate payment can make one account feel like the only problem, even when paying it would leave no money for rent, food, utilities, or another higher priority obligation. Review the complete debt picture before making a major decision.
Brock Legal works in bankruptcy and consumer finance, which allows the firm to evaluate collection behavior and the underlying financial problem rather than treating them as unrelated issues.
Bankruptcy Attorney Near Me Help With Repeated Calls
Repeated unwanted calls may also fall under separate protections; see our telephone solicitor harassment resources for more information. The law that applies can depend on whether the caller is a debt collector, telemarketer, original creditor, automated system, or another type of business.
Create a simple record. Note the date, time, number, caller name, company, and what was said. Save voicemail recordings and screenshots of missed calls. If you tell a collector that you are represented by an attorney, record when and how you provided that information.
Avoid making statements you do not understand just to end a call. You do not need to provide bank account access, debit card information, or an immediate payment simply because a caller demands it. If you believe the debt is yours but cannot afford the proposed arrangement, take time to review your options.
Preserve every written communication, including envelopes when the mailing date matters. Gather documents about the underlying account, including statements, contracts, settlement letters, prior disputes, and payment records. If there is a lawsuit, garnishment, or bank levy, bring the court papers immediately.
There can be time limits for bringing legal claims, so waiting indefinitely can make a strong issue harder to pursue. A free consultation can help you determine whether a debt collector has crossed the line and whether stopping one collector will solve the problem or a broader debt relief strategy is needed.
One more practical point is to keep the underlying debt and the collector’s conduct separate in your records. A collector may have accurate information about a balance while still using a method of collection that deserves legal review. The reverse can also happen: the calls may be professional, but the account itself may be wrong. Clear records help an attorney evaluate both questions without confusing one issue for the other.
If collection pressure is affecting several accounts at once, bring a complete creditor list to the consultation. That makes it easier to compare individual disputes with broader debt relief options and choose a response that fits the whole financial picture.
Frequently Asked Questions About the Fair Debt Collection Practices Act
Does the FDCPA apply to every creditor?
No. The FDCPA generally applies to qualifying debt collectors collecting consumer debts, and the rules can differ for original creditors collecting their own accounts. Other federal or state laws may still apply even when the FDCPA does not. The collector’s identity and role should be reviewed before drawing a conclusion.
Can a debt collector call me at work?
There are restrictions on collection communications, including circumstances where a collector knows that an employer prohibits such calls. The details matter. If calls at work are creating a problem, document them and tell the collector and your attorney about the situation.
What if the debt collector is trying to collect a debt that is not mine?
Do not simply pay it to make the calls stop. Save the notice, identify the claimed original creditor, review your credit reports, and consider a written dispute or validation request. If identity theft may be involved, additional credit reporting and fraud steps may be necessary.
Does an FDCPA violation erase the debt?
Not automatically. Collection conduct and the validity of the underlying debt are separate issues. A collector may violate consumer protection law while the debt itself remains enforceable. An attorney can evaluate both questions.
Can bankruptcy stop debt collection calls?
Filing bankruptcy generally triggers an automatic stay that stops many covered collection actions. Bankruptcy is a larger financial remedy, not simply a penalty against one collector, so eligibility, debts, assets, income, and goals should be reviewed before filing.
Contact Brock Legal About Unfair Debt Collection
You do not have to decide whether collection conduct is legal based on a stressful phone call or a threatening letter. Save the evidence, review the debt, and get advice about the law that applies. Sometimes the solution is a consumer protection claim or dispute. Sometimes the larger problem calls for bankruptcy or another debt relief strategy.
Think a debt collector violated your rights? Contact Brock Legal today for a free consultation. We help Indiana consumers understand unfair debt collection, credit reporting issues, bankruptcy, and practical options for resolving debt without letting collection pressure dictate every financial decision.
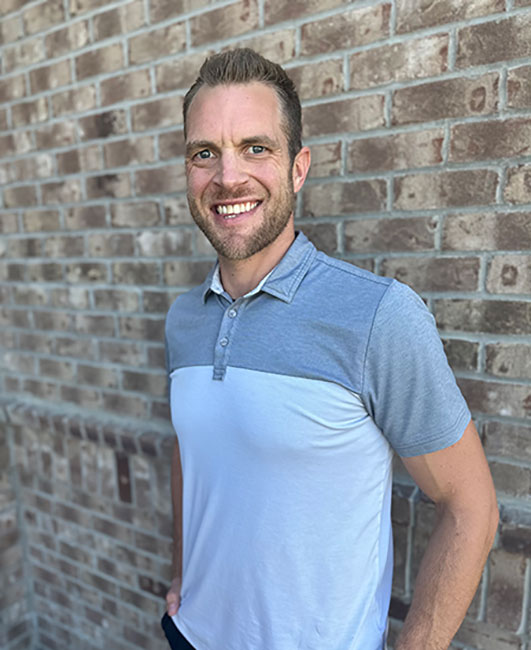
Attorney S. Zachary T. Brock
Attorney S. Zachary T. Brock
Zach empowers individuals faced with financial challenges by providing them with effective solutions and unwavering support in the areas of consumer finance and bankruptcy law.
By actively listening and empathizing with each client, Zach works to gain a deep understanding of every individual or family’s unique circumstances. This helps him tailor his legal strategy to best meet the needs of each client.
“No matter what may be weighing you down financially, Brock Legal is here to help. My mission is to help navigate you through whatever stressful circumstance you may be faced with, by offering unparalleled education and service in the areas of consumer finance and bankruptcy law. Let us show you how our firm can help. Contact Brock Legal today!”
-Zach