Identity Theft and Fraud What to Do If You Are a Victim
by Attorney S. Zachary T. Brock
Table of Contents
Identity Theft and Fraud Help for Indiana Consumers
Discovering an account you never opened, a credit card charge you did not make, or a collection notice for someone else’s debt can be unsettling. Identity theft often creates several problems at once. You may need to stop new fraud, protect bank and credit accounts, correct credit reports, respond to collectors, and preserve evidence for future disputes.
If you’ve discovered fraudulent accounts or charges, our identity theft and fraud services can help you take immediate action to limit the damage. The first hours and days matter because a thief may still have access to information that can be used to open additional accounts or take over existing ones.
Brock Legal, LLC helps consumers in Indianapolis and across Central Indiana address financial problems connected to fraud, inaccurate credit reporting, and debt collection. Not every identity theft problem requires bankruptcy, and not every suspicious account is handled the same way. The goal is to identify what happened, stop additional damage, and create a clear record that supports every dispute you make.
Credit Report Disputes Start With Immediate Fraud Protection
When you first discover identity theft, focus on stopping access and preserving information. Contact the financial institution connected to any unauthorized transaction and ask what fraud procedures apply. Change passwords on affected accounts and on the email account used for password resets. Use unique passwords and enable stronger authentication where available.
• Place appropriate fraud alerts or security freezes with the major credit bureaus when the circumstances call for them.
• Review bank, credit card, loan, and payment app activity for transactions you do not recognize.
• Save screenshots, statements, emails, letters, and text alerts that show suspicious activity.
• Write down the date you discovered the problem and each company you contacted, including confirmation numbers.
Review all three major credit reports rather than assuming the problem appears in only one place. Fraudulent debts often show up on your credit report; our credit report disputes team can help you correct inaccurate information.
The exact response depends on what information was stolen. A compromised credit card number is different from a stolen Social Security number, tax identity problem, or full account takeover. The more information you have about what was exposed, the easier it is to choose the right protections.
Consumer Finance Assistance for Fraudulent Accounts
Once immediate access is controlled, build a list of every account affected by the theft. Separate legitimate debts from accounts you did not open and legitimate accounts containing unauthorized charges. That distinction helps you communicate clearly with creditors, collectors, and credit bureaus.
• Ask each creditor or collector for the information needed to identify the account.
• Compare addresses, dates, application details, transaction locations, and contact information with your own records.
• Keep disputes factual and explain what information is inaccurate and what correction you are requesting.
• Retain copies of everything sent and every response received.
If fraudulent debt has become unmanageable, broader consumer finance assistance or bankruptcy options may also be worth exploring. Before considering bankruptcy for a fraud related balance, however, determine whether the debt should be attributed to you at all. Bankruptcy should not be used as a substitute for disputing an account that was never yours.
If a company rejects a dispute, do not assume the matter is finished. Review the explanation, determine what evidence is missing, and consider legal help when inaccurate reporting or collection continues.
Bankruptcy Attorney Help When Collectors Pursue Fraudulent Debt
Identity theft can become even more stressful when a fraudulent account is sold to collections or results in a lawsuit. A collector may have limited information about how the account was opened, so you may need to repeat the fraud history and provide documentation.
• Save every collector communication, including letters, emails, texts, and voicemail.
• Note the caller’s company, number, date, time, claimed creditor, and amount.
• Ask for written information about the debt rather than relying only on a phone conversation.
• If you receive court papers, record the response deadline immediately and get legal advice.
Acting quickly matters; contact our team as soon as you suspect identity theft. If you receive a summons, garnishment notice, or other court paper, treat the deadline seriously even if you know the account is fraudulent. A credit bureau dispute does not automatically pause a lawsuit.
Do not agree that the debt is yours merely to end a call. Statements and payment arrangements can have consequences, and the right response depends on the account and procedural posture.
A bankruptcy attorney who also handles consumer finance issues can help separate legitimate debt relief needs from fraud disputes. If you have substantial valid debt in addition to identity theft accounts, both problems may need attention, but they should not be mixed together without analysis.
Indiana Credit Report Disputes After Identity Theft
Credit reports often become the place where identity theft continues to cause damage long after the original fraud is discovered. A fraudulent account can affect lending decisions, apartment applications, insurance, and other financial opportunities.
Look for accounts you do not recognize, unfamiliar addresses, incorrect names, and hard inquiries you did not authorize.
Check balances, account status, dates, and creditor names for information that does not match your records.
Keep copies of the report showing each disputed item before you send a correction request.
Save the bureau or furnisher’s response and compare the corrected report with the original.
When disputing an item, identify the specific error instead of sending a vague statement that the report is wrong. Keep copies of the report, dispute, supporting identity theft records, and investigation results.
If a corrected account reappears, document that too. A recurring error can be especially important because it shows that the problem was previously raised.
Do not assume that paying a fraudulent collection is the fastest way to repair credit. Payment can complicate the story and may not remove inaccurate information. Get advice about disputing the account before using money needed for legitimate household expenses.
Identity Theft and Fraud Records You Should Keep
Good documentation makes every later step easier. Create one secure folder, digital or physical, for the identity theft matter and keep it organized by account.
Keep copies of credit reports before and after disputes so you can see whether information changed. Save creditor and collector letters, account statements, fraud affidavits, and written investigation results. Keep police or identity theft reports when you make them, along with confirmation numbers from government or financial institutions.
Preserve emails, text alerts, screenshots, and notices showing unauthorized activity. Maintain a timeline of calls and disputes with dates, names, numbers, and outcomes. Do not send original documents unless specifically required. Keep a copy of anything you provide.
Also protect the evidence itself. Identity theft files contain sensitive information, so do not store them in an unsecured shared folder or send full Social Security numbers through ordinary email unless a trusted professional gives you a secure method.
Resolving identity theft is often a process rather than a single phone call. Even after the fraudulent account is closed, watch credit reports, verify that balances are corrected, and respond if the account is transferred to another collector. Avoid companies that promise an instant credit reset or ask for large upfront fees to create a new identity.
Identity theft can also affect legitimate accounts when lenders react to sudden changes in a credit file. A bank may freeze access, replace cards, request additional verification, or temporarily restrict transactions. Those steps can be frustrating, but they may be part of protecting the account while fraud is investigated. Keep records of those conversations too, especially when a legitimate payment or account is disrupted.
If you are preparing for a major financial transaction such as a mortgage, apartment application, or vehicle loan, allow extra time for identity theft disputes to be reviewed. Do not wait until the day of an application to check whether fraudulent information remains. Early review gives you time to gather documents and address errors before they affect an important decision.
Frequently Asked Questions About Identity Theft and Fraud
What should I do first if I discover identity theft?
Secure affected accounts, change passwords, contact the relevant financial institutions, and review your credit reports. Consider fraud alerts or security freezes when appropriate. Preserve evidence and create a written timeline so later disputes are consistent and supported.
Should I freeze my credit after identity theft?
A security freeze can be useful when personal information may be used to open new accounts because it restricts access to your credit file for new credit decisions. Whether to freeze all reports depends on your situation and upcoming credit needs. Keep the information needed to lift a freeze securely.
How do I dispute a fraudulent account on my credit report?
Identify the exact account or information that is inaccurate, explain that identity theft is involved, and provide appropriate supporting records. Keep copies of what you send and the response. If the information is not corrected, an attorney can review the investigation and determine what additional steps may be available.
Should I pay a fraudulent collection account to make it go away?
Usually you should first determine whether the debt is actually yours and how to dispute it. Paying a fraudulent account may not correct inaccurate reporting and can complicate the record. Get advice before using household funds to satisfy an obligation created by someone else.
Can bankruptcy help if identity theft happened while I also have legitimate debt?
Possibly. Identity theft and legitimate debt should be separated first. Bankruptcy may help with qualifying debts that are actually yours, while fraudulent accounts may require disputes or other consumer remedies. A lawyer can review both issues and help avoid treating fraudulent debt as a legitimate obligation.
Contact Brock Legal for Identity Theft and Fraud Help
Identity theft can make your finances feel uncertain because you may not know which account will appear next. A methodical response helps. Secure access, document what happened, dispute inaccurate information, and respond promptly to collectors or court papers.
Think you’re a victim of identity theft? Contact Brock Legal today for help protecting your finances. We help Indiana consumers address identity theft, credit report disputes, collection problems, and legitimate debt issues so they can restore control without letting fraudulent accounts define their financial future.
Attorney S. Zachary T. Brock
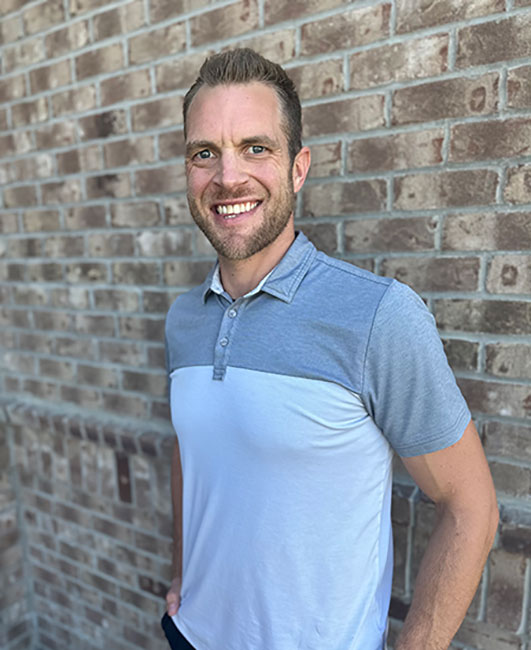
Attorney S. Zachary T. Brock
Zach empowers individuals faced with financial challenges by providing them with effective solutions and unwavering support in the areas of consumer finance and bankruptcy law.
By actively listening and empathizing with each client, Zach works to gain a deep understanding of every individual or family’s unique circumstances. This helps him tailor his legal strategy to best meet the needs of each client.
“No matter what may be weighing you down financially, Brock Legal is here to help. My mission is to help navigate you through whatever stressful circumstance you may be faced with, by offering unparalleled education and service in the areas of consumer finance and bankruptcy law. Let us show you how our firm can help. Contact Brock Legal today!”
-Zach