Can You Stop Foreclosure With Bankruptcy
by Attorney S. Zachary T. Brock
Table of Contents
Chapter 13 Bankruptcy Attorney Help When Foreclosure Is Moving Fast
A foreclosure notice can make it feel like the clock is running faster than you can think. If you are behind on mortgage payments in Indianapolis or elsewhere in Central Indiana, bankruptcy may give you legal breathing room, but timing matters. Filing a bankruptcy case can trigger the automatic stay, a federal protection that generally stops most collection activity, including many foreclosure proceedings, as soon as the case is filed.
For homeowners who want to keep their property, Chapter 13 is often the chapter that deserves the closest look. It can give eligible borrowers time to catch up on missed mortgage payments through a court supervised repayment plan while they continue making required ongoing payments. That does not mean every foreclosure can be stopped permanently. The loan, foreclosure stage, household income, home equity, prior bankruptcy filings, and ability to maintain future payments all matter.
Brock Legal, LLC helps Indiana homeowners look at the entire financial picture before deciding whether bankruptcy is the right response. The goal is not simply to delay a sale. It is to determine whether there is a workable path to protecting the home and building a budget that can last after the immediate crisis passes.
How Chapter 13 Bankruptcy Can Stop Foreclosure
Filing Chapter 13 bankruptcy triggers an automatic stay that immediately halts foreclosure proceedings, giving you time to catch up on missed payments. In a typical case, the stay prevents a mortgage lender from continuing a scheduled foreclosure action without first obtaining permission from the bankruptcy court.
• The repayment plan can address past due mortgage payments over time. Eligible borrowers may be able to cure missed payments through the plan rather than paying the entire arrearage at once.
• The automatic stay can stop many other collection actions too. Wage garnishments, lawsuits, calls, and other covered collection efforts may pause.
• A structured plan creates one financial framework. Mortgage arrears, certain taxes, vehicle obligations, and unsecured debts can be evaluated together.
• Homeowners can use the case to decide whether keeping the property is realistic. The future mortgage payment and plan payment need to fit the household’s actual income.
A Chapter 13 bankruptcy attorney can review the foreclosure timeline and determine whether there is enough time to file a complete case before a sale occurs. Waiting until the day before a scheduled sale creates unnecessary risk, particularly if required documents or counseling have not been completed.
Bankruptcy Attorney Review of the Automatic Stay
The automatic stay is powerful, but it has limits. It generally begins when the bankruptcy petition is filed. The lender receives notice of the case and must stop covered foreclosure activity unless an exception applies or the bankruptcy court later grants relief from the stay.
• Know the exact foreclosure stage and any scheduled sale date. A complaint, judgment, and scheduled sale present different timing concerns.
• Calculate how far behind the mortgage is. The arrearage helps determine whether a Chapter 13 plan is financially realistic.
• Identify other liens on the property. Second mortgages, tax liens, judgments, or association claims can affect the analysis.
• Disclose prior bankruptcy cases. Recent filings can change automatic stay protection and must be reviewed before relying on it.
Bring every foreclosure document to the consultation, including court papers, lender letters, reinstatement figures, and notices of sale. The more precise the timeline, the easier it is to evaluate what bankruptcy can actually accomplish.
Mortgage Modification and Bankruptcy Options
A mortgage modification may also be available as an alternative or complement to bankruptcy, depending on your lender. A modification changes one or more loan terms, which may include the interest rate, loan term, payment amount, or treatment of past due amounts.
• A homeowner may explore a modification while Chapter 13 provides protection from an active foreclosure, subject to court and lender requirements.
• Chapter 13 may create time to cure arrears when a lender will not offer a modification that solves the problem.
• Consumer finance assistance can help evaluate mortgage issues alongside other financial disputes instead of treating the home loan in isolation.
• The best option depends on affordability. A lower payment is useful only if the revised mortgage and other essential expenses fit the household budget.
A modification is not guaranteed, and applying for one does not always stop a foreclosure deadline. Do not assume that submitting paperwork to a mortgage servicer automatically protects a scheduled sale. Confirm the status and get legal advice if foreclosure is already pending.
Indiana Bankruptcy Lawyer Guidance on Chapter 7 and Home Equity
If your home has significant equity, Chapter 7 bankruptcy may not stop foreclosure the same way, so understanding the right chapter matters. Chapter 7 is primarily a liquidation and discharge process. It can temporarily trigger the automatic stay, but it does not provide the same multi year mechanism for curing mortgage arrears that Chapter 13 provides.
Home equity is also important because a Chapter 7 trustee reviews assets and exemptions. Indiana exemption law determines how much qualifying equity may be protected. A homeowner with substantial nonexempt equity can face risks that must be understood before filing.
Chapter 7 may still be useful in some situations. Discharging eligible unsecured debt may improve cash flow and help a homeowner stay current going forward. But if the central goal is catching up on a delinquent mortgage and keeping the property, Chapter 13 is often the more relevant conversation.
Brock Legal reviews the mortgage balance, estimated property value, liens, exemptions, income, expenses, and other debts before recommending a chapter. Bankruptcy should solve problems, not create a new property risk because the filing was rushed.
Foreclosure Help Before a Sheriff Sale
Time is critical in foreclosure cases; contact our team as soon as possible to explore your options. The earlier you ask for foreclosure help, the more time there is to review alternatives and prepare correctly.
• Gather the foreclosure complaint, judgment, sale notice, and recent court documents so the legal timeline is clear.
• Bring current mortgage statements and a recent reinstatement or payoff quote, if available.
• Prepare recent pay stubs, tax returns, bank statements, and a realistic monthly expense list.
• Include information about every other debt, including car loans, taxes, credit cards, medical bills, judgments, and support obligations.
Do not transfer the home, cash out retirement funds, or make unusual payments to selected creditors simply because a foreclosure deadline is approaching without first understanding the consequences. Decisions made under pressure can affect bankruptcy options.
Stopping a foreclosure is only the first question. The next question is whether the household can afford the home after the case is filed. A realistic review should include utilities, insurance, taxes, food, transportation, health care, childcare, and irregular expenses such as repairs. Brock Legal works with clients throughout Indianapolis and surrounding Indiana communities to understand what they want to protect and what their income can realistically support.
A homeowner should also think beyond the next court date. If Chapter 13 is being considered, the household needs a plan for staying current once the case begins. That may mean reviewing escrow changes, insurance costs, property taxes, utilities, repairs, and other expenses that are easy to underestimate when the immediate focus is stopping a sale. A plan that works only on paper can become difficult to maintain over several years.
It is also important to keep communicating with your attorney after filing. New lender notices, changes in income, insurance problems, or unexpected expenses should not be ignored. Chapter 13 is a court supervised process, and problems are usually easier to address when they are raised early. The goal is to use the protection of bankruptcy to create stability, not simply move the foreclosure problem a few months into the future.
For many Indianapolis homeowners, that broader review is what makes legal advice valuable. The question is not only whether bankruptcy can stop foreclosure today. It is whether the chosen strategy gives the family a realistic chance to keep the home tomorrow.
Frequently Asked Questions About Bankruptcy and Foreclosure
Can Chapter 13 stop a foreclosure sale?
Chapter 13 can trigger the automatic stay and stop many foreclosure proceedings if the bankruptcy is filed before the sale and the stay applies. Timing is critical. The case must also be supported by a workable repayment plan, and the lender can ask the court for relief from the stay in some circumstances.
How does Chapter 13 help me catch up on missed mortgage payments?
Eligible homeowners can generally propose a repayment plan that cures mortgage arrears over the life of the Chapter 13 case while required ongoing mortgage payments continue. The amount owed, income, other debts, and plan requirements determine whether that approach is affordable.
Can a mortgage modification stop foreclosure without bankruptcy?
A successful modification may resolve a delinquency, but merely applying for a modification should not be assumed to stop every foreclosure deadline. Servicing rules and the status of the case matter. If a sale is scheduled, get specific advice about the deadline.
Will Chapter 7 let me keep my house?
It depends on mortgage status, equity, exemptions, and the rest of the case. Chapter 7 may discharge eligible unsecured debt, but it does not provide the same repayment plan method for curing mortgage arrears as Chapter 13. Significant nonexempt equity can also create risk.
What should I do if my foreclosure sale is coming soon?
Gather the foreclosure papers, mortgage information, income records, and debt list and contact a bankruptcy attorney immediately. Do not wait for the final day. A lawyer needs enough time to determine whether bankruptcy applies and to prepare any required filing accurately.
Contact Brock Legal for Foreclosure Help in Indiana
Facing foreclosure can be frightening, but the earlier you understand your options, the more useful those options may be. Chapter 13 bankruptcy can stop many foreclosure actions through the automatic stay and may provide time to cure missed payments. Mortgage modification or another consumer finance strategy may also deserve consideration.
Facing foreclosure? Contact Brock Legal today for a free consultation to protect your home. We help Indiana homeowners review the foreclosure timeline, mortgage arrears, household income, other debts, and the practical cost of keeping the property so they can make an informed decision before the next deadline arrives.
Attorney S. Zachary T. Brock
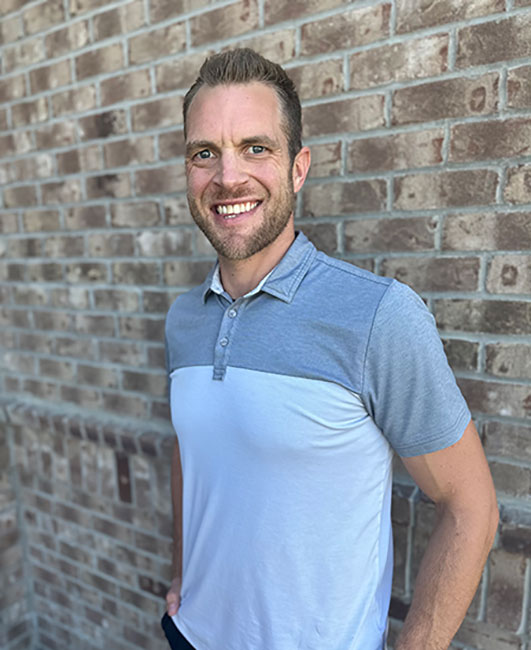
Attorney S. Zachary T. Brock
Zach empowers individuals faced with financial challenges by providing them with effective solutions and unwavering support in the areas of consumer finance and bankruptcy law.
By actively listening and empathizing with each client, Zach works to gain a deep understanding of every individual or family’s unique circumstances. This helps him tailor his legal strategy to best meet the needs of each client.
“No matter what may be weighing you down financially, Brock Legal is here to help. My mission is to help navigate you through whatever stressful circumstance you may be faced with, by offering unparalleled education and service in the areas of consumer finance and bankruptcy law. Let us show you how our firm can help. Contact Brock Legal today!”
-Zach